Quick answer After storm damage, work in order. Make sure everyone in the home is safe, document the damage from the ground for your insurer, arrange professional temporary protection to stop water from getting in, then call a licensed roofing contractor for a full inspection once conditions allow. Temporary measures only buy time. They are not a finished repair, and the sooner a licensed team assesses the roof, the smaller the long-term damage tends to be.
A tropical storm or hurricane can turn a sound South Florida roof into an active leak in a single afternoon. Wind lifts shingles, drives rain sideways into ridges and valleys, and throws debris hard enough to puncture decking. If you are searching for emergency roof repair in the hours after a storm, the most useful thing to understand is that there is a correct order of steps, and rushing past the early ones usually makes the insurance claim harder and the repair more expensive. This guide walks Broward County homeowners through that sequence, from the first safety check through the call to a licensed roofer, without a single instruction to climb up and patch anything yourself.
All America Construction Services has served Broward County homeowners since 2018 from its base in Coral Springs, and the pattern after every major storm is the same. The homes that end up with the least interior damage are almost never the ones where someone grabbed a ladder first. They are the ones where the owner stayed safe, recorded the damage properly, got professional temporary protection in place quickly, and let a licensed crew handle the actual repair.
Why Storm Damage in Broward County Becomes an Emergency So Quickly
Storm damage becomes a roofing emergency in Broward County because water intrusion compounds fast in a hot, humid climate, and a small opening on the roof can soak insulation, drywall, and framing within hours. Broward sits in one of the most hurricane-exposed corridors in the United States, and the same wind-driven rain that lifts a few shingles also finds the exact weak point where that opening lets water travel deep into the structure.
The homes we inspect across Coral Springs, Fort Lauderdale, Pompano Beach, Plantation, Coconut Creek, and Parkland tend to show a familiar set of storm signatures. Asphalt shingles are creased or torn loose along the windward slope. Barrel or flat tile is cracked or slid out of position, exposing the underlayment beneath. Metal flashing around chimneys, vents, and skylights is bent or gone. Soffit and fascia panels are pulled away, which lets wind and rain push up into the attic from the edge of the roof rather than the field. Each of these is a doorway for water, and in a Broward summer that water does not simply dry out.
The speed of the problem is what makes it an emergency. A ceiling stain that looks minor on the first evening can spread across a room by the next morning, because moisture wicks along the top of the drywall and follows the framing. Wet insulation loses its value and stays wet. Trapped humidity in a closed attic is the ideal setting for mold growth. That is why an emergency roof repair Broward County response is measured in hours, not days, and why the goal in the first stage is simply to stop more water from entering while the claim and the permanent repair get organized.
It also helps to understand that most South Florida roofs are built to a demanding standard and still take damage. Broward sits inside the High Velocity Hurricane Zone, so roofs here are installed to some of the toughest wind requirements in the country. That engineering reduces catastrophic failures, but it does not make a roof storm-proof. Sustained wind, pressure changes as gusts pass over the roof, and flying debris still lift edges, crack tile, and open seams. A roof performing exactly as designed can still let water in after a strong storm, which is why a post-storm inspection is worthwhile even when the roof looks mostly intact from the street.
The other reality is that the most costly storm damage is often the damage you cannot see from the ground. A slope that faced away from the wind can look untouched while the windward slope and the roof edges took the hit. Water that enters at a lifted ridge can travel several feet before it shows up as a stain, so the visible leak and the actual entry point are frequently in different places. This is a large part of why homeowners are advised to bring in a licensed inspector rather than judge the roof by what is obvious from the driveway.
There is also a legal and financial clock running from the moment the storm passes, which the section on insurance deadlines below covers in detail. The short version is that acting quickly protects both the house and the claim, and waiting rarely helps either one.
Make Sure Everyone Is Safe Before You Look at the Roof
Your first priority after a storm is safety, not the roof. Storm-damaged roofs, wet surfaces, weakened decking, hanging branches, and downed power lines create real hazards, and the roof will still be there once conditions are safe. Assess visible damage from the ground and from inside the home only.
Walk the interior first. Look for active drips, spreading ceiling stains, bulging drywall that may be holding water, and any sagging in the ceiling. A ceiling that is bowing downward can fail suddenly under the weight of pooled water, so keep people and pets out of that room and move furniture and electronics clear if you can do it safely. If water is near light fixtures, ceiling fans, or outlets, treat it as an electrical risk and keep the affected circuits off.
Outside, stay well away from any downed or sagging power line and assume every line is live. Watch for debris that is still shifting, loose fencing, and branches caught in the roof that could drop. Do not lean a ladder against a wet, storm-loosened roof edge, and do not climb up to look at the damage. Roofers who do this for a living use fall protection and wait for safe conditions, and there is nothing a homeowner needs to see from the roof surface that cannot be captured safely from the ground or by a licensed inspector.
Once you have confirmed everyone is safe and the immediate interior risks are contained, you are ready for the step that protects your money as much as your home, which is documentation.
How to Document Storm Damage the Way Your Insurer Needs
Document the damage thoroughly before anyone touches it, because your photos and notes are the backbone of your insurance claim. FEMA advises homeowners to record damage with photographs, keep repair estimates, and save receipts for any supplies or temporary protection used to keep the home safe, since that record is what supports a claim. Good documentation is the difference between a smooth claim and a disputed one.
Photograph Everything From Ground Level
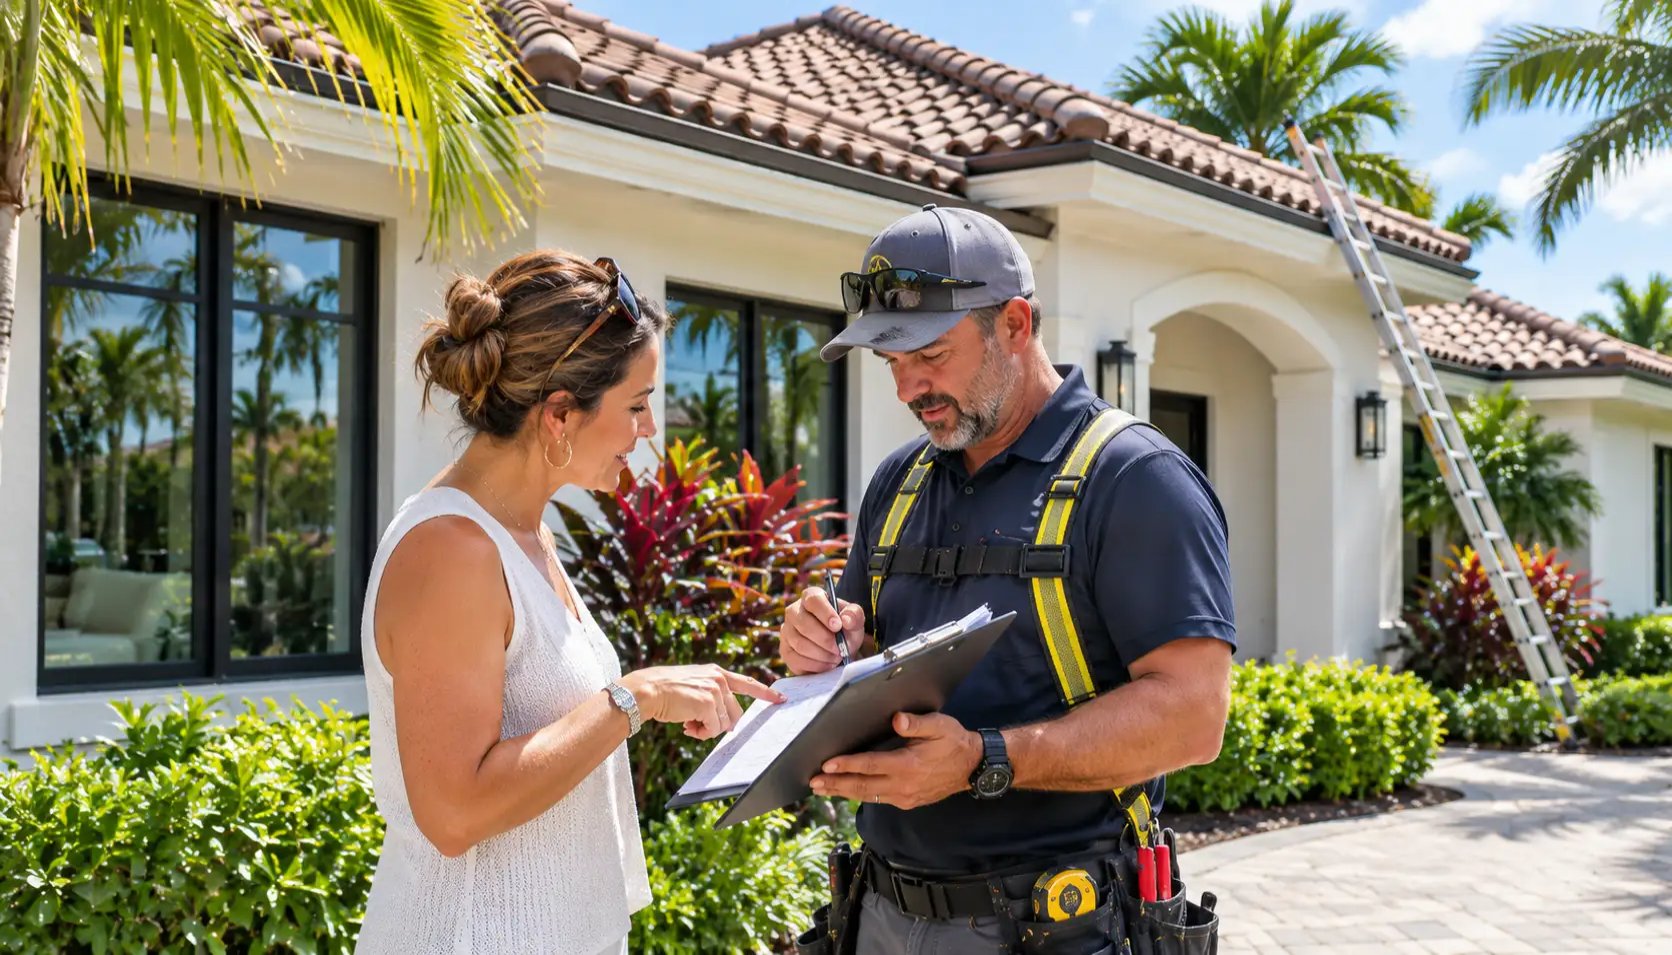
Photograph the damage from ground level and from inside the home, in a mix of wide shots and close-ups. Wide shots establish the overall scene, which slope was hit, how much of the roof is affected, and where debris landed. Close-ups capture the specific evidence an adjuster looks for, such as torn shingles, displaced tile, bent flashing, a punctured section, and interior water stains. Use your phone camera, keep the timestamp on, and take more images than you think you need. If you had recent photos of the roof in good condition, set those aside too, because a clear before-and-after comparison strengthens the file.
Do not forget the inside of the house and the areas that are easy to overlook. Photograph water stains on ceilings and walls, damaged flooring, and any belongings that were ruined, since contents damage can be part of the claim. Capture the attic from a safe vantage point if you can reach it without risk, because daylight through the deck or wet insulation is powerful evidence. Video walkthroughs help as well, especially when you narrate what you are seeing and when you noticed it. The goal is a complete record that an adjuster who never saw the storm can still understand at a glance.
Write a Simple Timeline of the Storm and the Damage
Write down what happened and when, in plain language. Note the date and rough time the storm hit, when you first noticed each leak or damaged area, and any steps you took to limit the damage. This timeline matters because Florida measures claim deadlines from the date of loss, which for a hurricane is generally the day the storm made landfall rather than the day you discovered the problem. A short, dated record removes any argument later about when the damage occurred.
Save Receipts for Any Temporary Protection
Keep every receipt tied to the storm. That includes the cost of professional tarping or board-up, any water extraction or drying, a hotel stay if the home is unlivable, and materials a licensed contractor uses to secure the property. Reasonable emergency measures to prevent further damage are commonly reimbursable under Florida homeowner policies, but you have to prove what you spent. File the receipts with your photos and timeline so the whole claim lives in one place.
Florida Insurance Claim Deadlines Broward Homeowners Should Not Miss
Report storm damage to your insurer as soon as possible, because Florida law now sets tight deadlines for property insurance claims. Under Florida Statute 627.70132, a homeowner generally has one year from the date of loss to give the insurer notice of a new or reopened claim, and 18 months for a supplemental claim. Your specific policy may set its own reporting window as well, so read it and notify your insurer without waiting.
The practical takeaway is that early notice protects your claim. Contacting your insurance company promptly gets an adjuster assigned, starts the file while the evidence is fresh, and gives you time to gather estimates before any deadline pressure. Late notice, by contrast, can give an insurer grounds to question or reduce a claim, even when the damage is genuine.
Standard Florida homeowner policies typically cover sudden storm damage from hurricanes, tropical storms, wind, and falling debris, though every policy has its own limits, deductibles, and exclusions. Broward County homeowners often carry a separate, percentage-based hurricane deductible that applies once a named storm is involved, which can be considerably higher than the standard deductible. Knowing your deductible before you file helps you plan the repair realistically. If any part of your coverage is unclear, ask your agent to walk you through it rather than guessing, since the answer shapes how the repair gets scoped.
A licensed roofing contractor who works in Broward regularly can be a real asset during this stage. A thorough inspection report, with clear photos and a written scope, gives your adjuster the documentation needed to evaluate the claim fairly and helps make sure nothing on the roof gets overlooked.
Temporary Risk Control That Buys Your Home Time
Temporary protection exists to stop further water intrusion until a permanent repair can be scheduled, and it should be installed by a professional rather than a homeowner on a ladder. Getting a proper cover in place quickly is often the single most valuable thing that happens in the first day after a storm, because it freezes the damage where it is instead of letting it spread through the house.
What Professional Temporary Protection Involves
Professional temporary protection usually means securing a heavy-duty tarp or reinforced sheeting over the damaged area, fastened and sealed so wind cannot peel it back and rain cannot run underneath. Depending on the damage, a crew may also board up an opening, clear debris that is trapping water, or set up drying equipment inside. After major federally declared disasters, programs such as the FEMA and Army Corps of Engineers Operation Blue Roof provide temporary sheeting for eligible homes, though that program does not cover materials like slate, clay tile, or other roofs where a tarp is impractical, and it is not a substitute for a permanent repair. For most Broward homeowners, the faster route is a licensed local roofer who can install a secure temporary cover the same day and then handle the full repair. FEMA guidance on documenting and temporarily protecting storm damage reinforces the same principle, which is to make the home safe, protect it from further loss, and keep records of what was done.
What Temporary Protection Cannot Do
Temporary protection cannot restore the roof, and treating a tarp as a fix is one of the more expensive mistakes homeowners make. A cover keeps water out for a limited time, but it does nothing for the torn underlayment, the loosened flashing, the cracked tile, or the wet decking underneath. Sun, heat, and the next round of afternoon storms will wear a tarp down, and a cover that was solid in week one can start leaking by week four. A well-installed temporary cover should be viewed as a bridge to a scheduled, permanent emergency roof repair Broward County homeowners can rely on, not as the destination.
When Temporary Protection Is Not Enough
Temporary protection is not enough once the damage reaches the roof structure, spreads across multiple areas, or sits on a roof that was already near the end of its life. At that point the right question shifts from how to cover the roof to whether it needs a substantial repair or a full replacement, and that is a decision for a licensed inspection rather than a guess from the ground. The table below outlines common storm-damage situations and the direction each one usually points.
Storm Damage Situation | What It Usually Means | Typical Direction |
A few lifted or missing shingles in one area | Localized surface damage | Temporary cover, then a scheduled repair |
Cracked or displaced tile with underlayment showing | Water barrier is compromised | Prompt professional inspection and repair |
Multiple leaks or leaks far from the visible damage | Water is traveling through the structure | Full inspection before any repair scope is set |
A sagging roofline or soft, spongy decking | Possible structural or moisture damage | Urgent assessment, replacement often likely |
Widespread damage on an older, worn roof | Repair may not be cost-effective | Repair-versus-replace evaluation with your insurer |
A few signals point strongly toward urgent professional attention rather than a wait-and-see approach. Daylight visible through the roof deck from inside the attic means the roof envelope is open. Water appearing in rooms that are nowhere near the obvious damage means moisture is moving through the framing. A ceiling or roofline that is visibly sagging suggests the structure itself may be affected. Any of these deserves a same-day call to a licensed contractor, because the cost of waiting climbs quickly once water is inside the structure.
The repair-versus-replace question is genuinely case by case, and it depends on the roof’s age, the material, how widespread the damage is, and what your policy covers. A licensed roofer who documents the condition honestly, section by section, gives you and your insurer the information to make that call correctly. Beware of any pitch that jumps straight to a full replacement without an inspection, and be equally wary of a bargain patch that ignores structural signs. The right answer comes from an inspection, not a sales script.
Choosing a Licensed Roofing Contractor in Broward County
Choose a licensed, insured, Broward-based roofing contractor with real storm and insurance-claim experience, and confirm that license before work begins. Florida requires roofing contractors to be licensed, and you can verify a company’s credentials through the state licensing system. A licensed local contractor is not just a legal box to check. It is your best protection against the storm-chasing crews that appear after every hurricane, take a deposit, and disappear.
Look for a contractor that is physically based in the area and answers the phone during a storm response, not a call center hundreds of miles away. Ask how soon they can get a temporary cover on the roof, how they document damage for insurance, and whether they will meet your adjuster on site. A team that already works across Broward County knows the local building department requirements, the High Velocity Hurricane Zone rules that shape how repairs are done in South Florida, and the products that actually hold up to coastal wind. You can review how a local roofing team approaches storm response on the All America Construction roofing services page for Broward County.
What to Have Ready When You Call
Have your key information ready before you call so the contractor can help faster. Keep these items within reach.
• Your storm photos, interior and exterior, and your dated timeline of the damage
• Your insurance company name, policy number, and claim number if you have already filed
• A short description of where the leaks are and which rooms are affected
• Your address and the safest way to reach you if power or cell service is spotty
• Any earlier roof records, such as the age of the roof or a recent inspection report
With that in hand, a licensed crew can prioritize your home correctly, get temporary protection scheduled, and set up a full inspection. All America Construction Services works with Broward homeowners through exactly this sequence, from the first storm-response call in Coral Springs and across the county to the permanent repair.
Working Through the Insurance Claim With Your Roofing Contractor
The smoothest storm recoveries happen when your roofing contractor and your insurance adjuster are working from the same set of facts. Once temporary protection is on the roof and your claim is filed, ask your contractor to prepare a detailed inspection report with photographs and a written scope of the damage. That document gives the adjuster a clear, professional basis for evaluating the claim and reduces the back-and-forth that drags a repair out.
Where possible, have the contractor present when the adjuster inspects the roof. A roofer who can point out storm-related damage in person, and explain why a particular area needs repair or replacement, helps make sure the assessment reflects the true condition of the roof. This is not about inflating a claim. It is about making sure legitimate storm damage is captured accurately the first time, so you are not fighting for a supplemental claim months later.
A few mistakes tend to complicate storm claims, and they are easy to avoid once you know them. Do not throw away damaged materials before they are documented, since the debris itself can be evidence. Do not authorize a full permanent repair before your insurer has had a chance to inspect, unless emergency work is needed to prevent further damage, in which case you photograph first and keep the receipts. Do not sign over your claim rights to a contractor without understanding exactly what you are agreeing to. And do not accept the first settlement figure as final if your contractor’s inspection shows the scope was underestimated, because that is precisely what the supplemental claim window exists for.
Keep your own records organized throughout. Save every email and letter from your insurer, note the dates of calls and who you spoke with, and keep the photo, timeline, and receipt file current. A homeowner who stays organized, works with a licensed local contractor, and moves promptly on both the temporary protection and the claim gives the whole process the best chance of a fair, timely outcome. That is the real value of handling an emergency roof repair in Broward County the right way, one careful step at a time.
Call All America Construction Services at (954) 225-6087 to schedule a licensed storm-damage roof inspection for your Broward County home.
Frequently Asked Questions
What should I do first when my roof is leaking during a storm in Broward County?
Make sure everyone is safe first, then contain the interior damage. Move people, pets, electronics, and furniture away from active leaks and any sagging ceiling, and keep affected electrical circuits off if water is near fixtures or outlets. Do not climb onto a wet, storm-damaged roof. Once conditions are safe, photograph the damage from the ground and from inside, then call a licensed roofing contractor to install temporary protection and inspect the roof.
How long do I have to file a storm damage insurance claim in Florida?
Under Florida Statute 627.70132, a homeowner generally has one year from the date of loss to give the insurer notice of a new or reopened claim, and 18 months for a supplemental claim, with the date of loss for a hurricane usually being the day it made landfall. Your individual policy may set its own reporting window, so report the damage to your insurer as soon as possible rather than waiting near a deadline.
Does homeowners insurance cover emergency roof repair after a storm?
Standard Florida homeowner policies typically cover sudden storm damage from hurricanes, tropical storms, wind, and falling debris, and reasonable emergency measures to prevent further damage, such as professional tarping, are commonly reimbursable. Coverage still depends on your specific policy, its exclusions, and your deductible, and many Broward homeowners carry a separate percentage-based hurricane deductible. Keep all receipts and ask your agent to confirm exactly what your policy covers.
Is a tarp enough to fix my roof until I can afford a full repair?
No. A tarp is temporary protection that keeps water out for a limited time, not a repair. It does nothing for torn underlayment, loosened flashing, cracked tile, or wet decking underneath, and sun and repeated storms wear covers down within weeks. Treat a professionally installed tarp as a bridge to a scheduled permanent repair, and get a licensed inspection to determine what the roof actually needs.
Should I get on the roof to check the damage myself?
No. Storm-damaged roofs are slippery, structurally weakened, and often near downed power lines or shifting debris, and a fall or electrical contact is a serious risk. Everything you need for an insurance claim can be captured safely from the ground and from inside the attic, and a licensed roofer with proper fall protection can inspect the roof surface. Keep yourself safe and let a professional handle anything that requires being on the roof.
How do I choose a trustworthy roofing contractor after a hurricane in Broward County?
Choose a licensed, insured contractor that is based locally and has real storm and insurance-claim experience, and verify the license before any work starts. Be cautious of storm-chasing crews that appear after a hurricane, request a large deposit, and pressure you to sign quickly. Ask how fast they can install temporary protection, how they document damage for insurance, and whether they will meet your adjuster on site. A contractor that already works across Broward County will know the local permitting and High Velocity Hurricane Zone requirements.
How fast can someone respond for emergency roof repair in Broward County?
Response times vary with storm severity and demand, since a widespread hurricane keeps every local roofer busy at once. That is exactly why calling early matters. Contacting a licensed Broward-based contractor as soon as it is safe gets your home into the queue for temporary protection and a full inspection sooner. Have your photos, timeline, address, and insurance details ready so the contractor can prioritize your home and act quickly.